Highlight of Mississauga Condo Project Sold After Prolonged Insolvency
📅 4 days ago
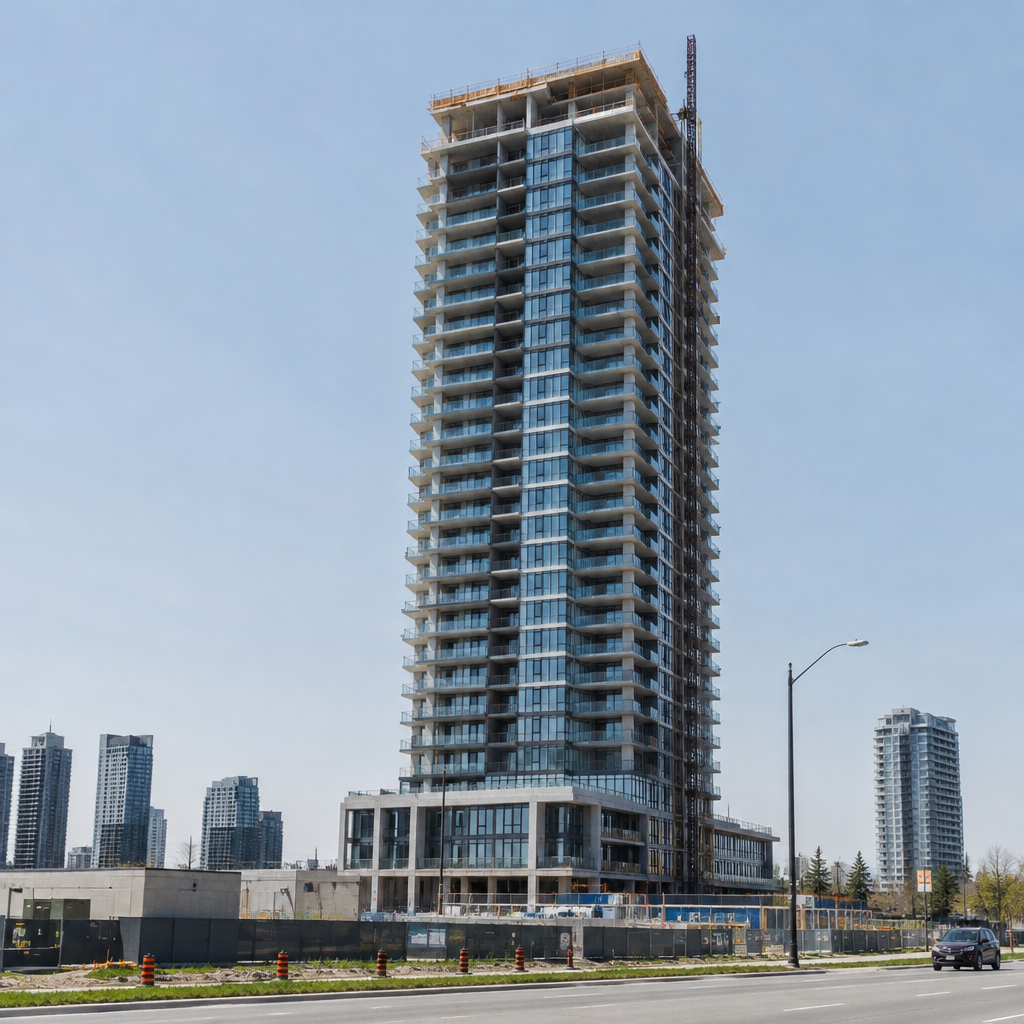
The Highlight of Mississauga condo project, which faced significant financial and construction challenges, has been sold after being placed under creditor protection.
The Highlight of Mississauga, a substantial condominium project located at 4064, 4070, and 4078 Dixie Road in Mississauga, has officially changed ownership following a protracted period of insolvency. This development, which is situated directly across from Rockwood Mall, was initially spearheaded by Hazelton Development Corporation (HDC), under the leadership of President Du Zhixian, also known as Joe Du. Court filings reveal that HDC has been grappling with financial difficulties since mid-construction, prompting the company to seek creditor protection more than four years ago.The project was ambitious, aiming to construct a 14-storey building comprising 265 strata units, which included both condominiums and townhomes. Sales efforts began around May 2018, resulting in a remarkable pre-sale of 261 out of 265 units, generating revenue amounting to $111,633,085. However, construction officially commenced in September 2019, with an anticipated completion date set for April 2021. Unfortunately, the project encountered numerous delays, largely attributed to liquidity issues, which ultimately led HDC to file for creditor protection under the federal Companies’ Creditors Arrangement Act (CCAA) in April 2022, by which point construction had reached Level 12.
To finance the project, HDC secured a first-ranking mortgage through Meridian Credit Union in May 2019, amounting to a construction loan of up to $50 million, complemented by a standby letter of credit facility worth up to $2 million. Additionally, a second mortgage was arranged with Centurion Mortgage Capital Corporation, which transitioned into Centurion Asset Management in 2024, for up to $19.9 million in construction funds, alongside a cost-overrun facility of $3.5 million. At the time of filing for creditor protection, HDC reported debts of approximately $20,694,142 to Meridian and $20,673,626 to Centurion, totaling $41,367,768, with interest accruing. Furthermore, HDC disclosed that certain shareholders provided about $6.35 million in loans from September 2019 to March 2022, and Triumph Eastern Investments Inc. advanced six loans during the same period.
The onset of the COVID-19 pandemic in early 2020 exacerbated HDC's challenges, leading to project delays communicated to purchasers as early as March 2020. Further delays followed, with notices issued in May 2021, November 2021, January 2022, and March 2022. The original construction budget was set at $101,183,823, but by November 2021, it had risen by $11,672,011 to a new total of $113,669,237. The budget increases were attributed to COVID-19-related delays, heightened supervision and management costs, and rising prices for materials and labor. Despite efforts to raise additional equity, HDC could not meet Meridian's debt-to-equity ratio requirements, leading to a halt in advances from the lender in July 2021.
In March 2022, the Du family acquired an 80% stake in HDC, subsequently introducing new management to stabilize the project. A month later, HDC sought creditor protection. By July 2022, Firm Capital, a Toronto-based non-bank lender, agreed to finance the project with a loan of up to $80 million, facilitating the resumption of construction. In February 2023, the court allowed presale purchasers two options: to proceed with their purchases under revised terms or terminate their agreements in exchange for a 12% premium on their deposits. Despite ongoing contractor disputes and delays, construction progressed to around 92.6% completion by February 2026. However, further challenges, including construction deficiencies and rising costs, raised questions about the feasibility of completing the project.
As of early 2026, most presale purchasers opted for the compensation route, leaving 197 unsold units and contractor lien claims totaling $10,802,325. A court-ordered sales process began in late February, with 15 potential buyers expressing interest. After negotiations, Firm Capital initiated discussions to acquire the project through a reverse vesting order, which involved purchasing the shares of HDC rather than the real estate directly. The total purchase price was estimated at around $74.3 million, including various floating amounts and cash considerations. The court hearing to approve the sale faced delays, ultimately receiving approval from the Ontario Superior Court on November 4.
🏷️
condominium
Construction
creditor protection
insolvency
Mississauga
Firm Capital
Hazelton Development Corporation
investment
real estate
housing market